

Blogs
Digital Photo Frame Market to Reach $235.6M by 2032 with 3.2% CAGR, Led by Asia Pacific
By PW Consulting, 2026-09-07
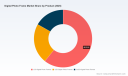
Navigating the Digital Photo Frame Market: Strategic Intelligence for 2026 Decision-Makers
The digital photo frame market stands at a pivotal inflection point as 2025 closes. What was once a niche home décor accessory has evolved into a connected lifestyle category, shaped by cloud integration, aging demographics, hospitality merchandising, and a tighter global supply chain. For executives mapping growth strategies, product roadmaps, and channel investments, the window to interpret structural shifts is narrowing. PW Consulting’s newly released Digital Photo Frame Market research translates over a decade of historical tracking and a forward-looking forecast horizon into a decision-ready intelligence toolkit. This article previews the strategic scope of the study, outlines the competitive forces reshaping the category, and explains why disciplined, data-grounded planning matters more than ever in 2026.
Sales Automation Tools Market
The Market Arc: From Recovery to Sustained Expansion
The category has demonstrated resilience through cyclical disruptions and demand shifts. Tracking the market from 2020 through 2025 reveals a trajectory that balances recovery with pockets of volatility, setting the stage for a measured but durable expansion phase. The latest forecast extends across 2026 to 2032, projecting a steady compound annual growth rate of 3.2 percent in USD terms. By the close of the forecast period, market revenue is expected to surpass the 235 million milestone, reflecting incremental but consistent value creation across consumer and commercial touchpoints. This trajectory signals more than a simple rebound: it indicates category maturation, where differentiation increasingly depends on connectivity, design language, and use-case alignment rather than screen size alone.
Calcium Hypophosphite Flame Retardants Market
For enterprise strategists, the implication is clear. Growth will not be uniformly distributed, and leaders who assume flat expansion will miss the pockets of accelerated adoption tied to specific applications and geographies. The research deliberately avoids surface-level aggregates, instead guiding readers toward the structural drivers, adoption bottlenecks, and channel dynamics that determine where returns materialize first. Strategic plans built on broad averages tend to over-index in mature segments and under-invest in emerging pockets; the report's frameworks are designed to correct that blind spot.
Canine Cancer Detection Market
Structural Shifts Reshaping the Category
Several forces are converging to redefine how digital photo frames are conceived, manufactured, and deployed. These are not isolated developments; they interact across product design, sourcing strategy, compliance burden, and end-user expectations. Understanding their interplay is essential for building a resilient 2026 plan.
Connectivity, Display Maturity, and Experience Design
The product landscape now spans LCD, LED, and OLED formats, each serving distinct experience expectations and cost profiles. LCD options continue to anchor volume-driven value propositions, while LED variants target brighter display performance and feature-rich interfaces. OLED solutions introduce premium contrast and form-factor flexibility, though they bring their own cost, supply, and durability considerations. Connectivity has become a baseline expectation rather than a premium feature. Wi-Fi-enabled sharing, cloud sync, touch interaction, and integration with digital assistants are increasingly expected in consumer-facing SKUs. Meanwhile, calendar, memo, and hybrid content modes are expanding the frame's role from passive display to a household utility. These experience upgrades influence design cycles, component selection, and software support roadmaps, which in turn affect time-to-market and post-launch maintenance costs.
Supply Chain Realities and Sourcing Pressure
The category is navigating lasting supply chain instability. Shipping disruptions, inventory carrying costs, and maritime insurance premiums have risen sharply during periods of geopolitical instability, placing heavy pressure on production planning and working capital. In response, manufacturers are diversifying sourcing footprints, investing in localized assembly, and evaluating alternative component materials to reduce exposure. At the same time, regional labor economics continue to shape pricing structures, particularly where OEM and contract manufacturing operations are concentrated. These conditions are changing the cost architecture of the category. Companies that rely on linear sourcing assumptions face margin compression and delivery volatility, while those that build flexibility into procurement, packaging, and logistics are better positioned to protect profitability without sacrificing availability.
Trade, Regulation, and Compliance as Strategic Variables
Geopolitical friction is no longer a peripheral concern. Ongoing trade disputes have accelerated the push to diversify supply chains, localize assembly where feasible, and adopt alternative materials for key components. Beyond tariffs and logistics, regulatory uncertainty around battery safety, electronic waste management, and device compliance is influencing development cycles and pricing strategies. The combined effect is a longer planning horizon and a higher threshold for launch readiness. Teams that treat compliance and sourcing as afterthoughts risk rework, delayed introductions, and fragile channel relationships. Those that embed regulatory and supply considerations into product definition and go-to-market planning can convert complexity into a competitive advantage by shipping with greater predictability and lower total cost of ownership.
Where Value Is Created: Segments, Use Cases, and Deployment Logic
The market's internal structure tells a more nuanced story than headline revenue figures suggest. Adoption varies by region, product format, and application context, and each axis carries distinct buyer motivations, purchasing cycles, and margin dynamics. The report deconstructs these dimensions to reveal where demand is concentrated, where substitution is most likely, and which segments offer the clearest paths to share gain.
Regional Demand Patterns
North America remains a significant demand center, supported by established consumer electronics retail channels, higher disposable income thresholds, and a mature connected-home ecosystem. Europe represents a structurally different environment, shaped by energy-conscious procurement, regulatory scrutiny, and varied retail configurations. Asia Pacific exhibits scale, channel diversity, and rapid iteration in connected display devices, making it both a volume opportunity and a competitive proving ground. Latin America and the Middle East and Africa add complexity through fragmented distribution, price sensitivity, and mixed infrastructure readiness. The interplay among these regions affects everything from SKU rationalization to channel partnerships and localization requirements. Executives with multi-region ambitions need to understand not just where volume sits today, but how relative attractiveness is likely to shift as pricing, connectivity, and compliance conditions evolve.
Product Formats and Application Contexts
On the product side, LCD remains a central volume anchor, but differentiation increasingly comes from feature integration, display quality, and software experience. LED and OLED variants target quality-tier positioning and specialized visual performance, each with trade-offs in cost, power, and manufacturing complexity. On the application side, residential deployments reflect emotional and lifestyle use cases: personal sharing, family memory curation, and home ambiance. Commercial uses extend into hospitality, retail merchandising, and branded engagement, where uptime, content management, and remote administration matter more than decorative finish. Institutional applications create additional requirements around durability, security, standardized content workflows, and procurement cycles. These contexts shape product requirements, support models, and pricing logic in fundamentally different ways, and a single product strategy rarely fits all three. The research maps these application-level dynamics in greater depth, with attention to the cost-to-serve, content management burden, and channel suitability that determine repeatable success.
Competitive Landscape: Capability, Positioning, and Pace
The market is highly concentrated among a small group of leaders, leaving limited room for undifferentiated entry. A handful of companies command the majority of reported share, while a broader set of challengers competes through niche positioning, product refresh cadence, connectivity features, and channel access. The report profiles the leading names shaping the competitive environment, drawing attention to the capabilities that differentiate them and the vulnerabilities that can open strategic openings.
- Aura emphasizes premium Wi-Fi-enabled frames with app-based photo sharing, long battery life, and paper-like matting. Its consumer lineup, including models such as Carver and Aspen, reflects a design-forward positioning aimed at customers willing to pay for experience quality and ease of sharing.
- Nixplay focuses on photo and video combination with cloud integration, offering touch-driven models with assistant support. Its approach appeals to users who want a hybrid content experience and connected convenience without creating a complex setup burden.
- Aluratek combines Wi-Fi and ePaper offerings with touchscreen and calendar features, and recently expanded its portfolio with updated Smart Wi-Fi Digital Calendar Photo Frames that integrate multiple household functions. This move highlights the category's gradual shift from single-purpose displays toward utility-oriented devices.
- Sungale supplies cloud and plug-and-play frames with a focus on straightforward deployment and accessible pricing. Its presence underscores the importance of simplicity, ease of setup, and value-led execution in price-sensitive and volume-oriented segments.
- PhotoSpring centers on instant setup and sharing for consumer frames, an approach designed to reduce friction in the purchase-to-use journey and lower the support load for retail and direct channels.
- Kodak addresses the market through licensed manufacturing of touchscreen frames, leveraging brand recognition while operating within a constrained product-development model.
- Digital Foci provides solutions across consumer and enterprise contexts, indicating that frames are increasingly considered not just as décor but as usable display infrastructure in specific organizational settings.
Beyond product features, competitive advantage increasingly depends on execution reliability. The recent launch activity from Aluratek illustrates how feature bundles and calendar integration can refresh a portfolio's relevance, but it also raises expectations for software updates, content management, and long-term support. In a concentrated market, small differences in reliability, setup experience, content ecosystem, and channel alignment can determine disproportionate share outcomes. PW Consulting's analysis examines these dynamics in greater depth, including how each player's positioning intersects with sourcing flexibility, regional readiness, and regulatory exposure.
Decision Intelligence for 2026: What the Report Delivers
The research is built to support concrete decisions rather than abstract trends. It pairs macro trajectory with segment-level logic, competitive benchmarking, and operational considerations that influence margin, risk, and speed. The aim is to help leaders cut through noise and prioritize with precision.
- Market sizing and trajectory across the historical and forecast periods, with forward-looking assumptions that clarify what drives the 3.2 percent CAGR path and how changes in pricing, adoption, or supply conditions could alter outcomes.
- Segment breakdowns by region, product format, and application, presented to expose relative concentration, substitution risks, and the practical implications of shifting demand across residential, commercial, and institutional contexts.
- Competitive profiling that maps player positioning, feature emphasis, deployment models, and the operational implications of stand-out capabilities or dependency risks.
- Industry dynamics covering sourcing pressure, logistics fragility, regulatory exposure, and labor-cost influences, tied directly to product planning, inventory strategy, and launch timing.
- Actionable interpretive guidance for pricing architecture, channel selection, localization, product refresh cadence, and risk mitigation in an environment where cost and compliance uncertainty remain elevated.
Readers looking for complete segment-level splits, company benchmarks, and scenario interpretation will find the full study provides the granularity needed to build internal business cases, channel plans, and procurement strategies. The executive preview here is intentionally high-level; the report itself contains the deeper dissection that turns observation into action.
Why the Full Study Matters Now
In 2026, the burden of proof is rising for both new product introductions and portfolio defenses. Teams must justify where to invest, which features to ship, how to price against concentrated incumbents, and how to hedge against sourcing and compliance disruption. Broad market narratives are insufficient in a category where value creation depends on experience differentiation, regional readiness, and supply chain resilience. The PW Consulting study is designed to provide the analytical scaffolding for these decisions.
This article previews the strategic contours; the full market research provides the detailed breakdown, the segment dissection, and the interpretive frameworks needed to translate market structure into executable plans. For executives seeking to prioritize investment, refine product strategy, and reduce exposure in an environment that rewards discipline, the report offers the depth required to move from observation to action.
For detailed analysis of this topic, please visit the official page: Digital Photo Frame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Spoil Detection Based Smart Label Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific spoil detection based smart label market is expected to grow significantly from USD 8,930 Million in 2020 to USD 16,230 Million in 2025 and is projected to reach USD 45,870 Million by 2035. This robust expansion is attributed to rising regulatory standards, e-commerce boom, and widespread supply chain digitalization. The period from 2025-2030 is anticipated to witness the fastest CAGR, driven by rapid IoT adoption and increased demand for food and pharma safety across APAC.
Read More - https://bussinessinsights.com/research-report/asia-pacific-spoil-detection-based-smart-label-market
Food & Beverages is the largest application segment, accounting for 47% of the Asia-Pacific spoil detection based smart label market in 2025. This is driven by heightened demand for quality assurance and safety in the perishable goods sector. Pharmaceuticals follow at 21%, supported by regulatory compliance and cold-chain management needs. Healthcare, Cosmetics & Personal Care, and Chemical applications jointly represent the remaining share, reflecting expanding use cases for real-time spoilage and authenticity monitoring.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-spoil-detection-based-smart-label-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Spoil Detection Based Smart Label Market industry?
The top five players in the Asia-Pacific Spoil Detection Based Smart Label Market are Insignia Technologies, Thinfilm Electronics, Evigence Sensors, Timestrip UK Ltd., and Avery Dennison. These companies provide innovative solutions for real-time food quality monitoring, leveraging advanced sensor technologies to ensure safety and transparency in the supply chain.
What is the Asia-Pacific Spoil Detection Based Smart Label Market growth?
The Asia-Pacific Spoil Detection Based Smart Label Market is witnessing robust growth, driven by increasing adoption in the food and beverage sector. For example, Insignia Technologies reported significant demand for its smart label solutions in 2023, owing to heightened consumer awareness around food safety and supply chain efficiency.
Which segment accounted for the largest Asia-Pacific Spoil Detection Based Smart Label Market share?
The food and beverages application segment held the largest market share in the Asia-Pacific Spoil Detection Based Smart Label Market. Smart labels are widely used in meat, poultry, dairy, and packaged foods to offer real-time spoilage alerts, enabling both retailers and consumers to monitor freshness and reduce food wastage.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting Report: Wood Furniture Market to Reach $449.74B by 2032, Growing at 4.95% CAGR
By PW Consulting, 2026-09-07
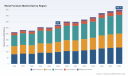
Navigating the Wood Furniture Market: Strategic Intelligence for 2026 Decision-Makers
The global wood furniture industry is entering a phase of strategic recalibration. As supply chains adapt to evolving trade policies, raw material costs fluctuate with timber market dynamics, and consumer preferences shift toward sustainable and space-optimized solutions, executives across retail, manufacturing, and commercial procurement face a complex choice matrix. In this environment, actionable intelligence is not a luxury. It is a prerequisite for capital allocation, portfolio positioning, and competitive execution.
Worldwide Oil Filter Plier Market
PW Consulting's newly released Wood Furniture Market research study provides a comprehensive, forward-looking analysis designed specifically to support enterprise decision-making through 2032. Built on a rigorous analytical framework spanning historical performance from 2020 to 2025 and a detailed forecast period from 2026 to 2032, this report equips leadership teams with the structural clarity needed to navigate volatility, identify high-value deployment pathways, and benchmark competitive positioning against an increasingly fragmented landscape.
Worldwide Residential Circuit Breakers Market
Market Architecture: Scale, Trajectory, and Structural Shifts
The wood furniture market has demonstrated resilience and measured expansion over the past half-decade. Historical data from 2020 through 2025 reveals a sector that recovered from early-cycle disruptions, stabilized through supply-side adjustments, and positioned itself for sustained growth. By 2025, total market revenue reached approximately 325.0 billion USD, reflecting the culmination of multi-year demand recovery and product mix evolution.
Metaverse Virtual Platform Market
Looking ahead, the forecast period projects continued expansion anchored by a compound annual growth rate of 4.95 percent. Revenue is expected to advance from 351.59 billion USD in 2026 toward 449.74 billion USD by 2032. This trajectory signals more than incremental growth; it reflects structural demand drivers, material substitution patterns, and regional rebalancing that will shape competitive dynamics for the next several years.
For executives, this macro perspective is useful, but the real strategic value lies in the granularity beneath the headline numbers. The report decomposes growth across product architectures, end-use environments, and geographic supply-demand corridors, revealing where volume concentration translates into margin opportunity and where fragmentation creates room for differentiated positioning.
What the Study Delivers: Operational Intelligence for the Enterprise
This research was engineered with practitioner utility in mind. Rather than offering a static snapshot, the study provides a living analytical toolkit that supports scenario planning, sourcing strategy, and go-to-market optimization. The scope encompasses:
- Historical baseline analysis (2020–2025) that isolates demand inflection points, pricing behavior, and product-mix transitions across the cycle, enabling leadership to distinguish structural shifts from temporary volatility.
- Multi-horizon forecasting (2026–2032) that maps revenue pathways under baseline and alternative demand scenarios, providing a defensible basis for capacity planning, inventory strategy, and channel investment.
- Type-level segmentation analysis that evaluates how solid wood, wood-based panel constructions, and miscellaneous furniture categories contribute to overall revenue composition, with implications for manufacturing footprint, material sourcing, and pricing architecture.
- Application-driven demand mapping that examines how home, office, and commercial/hospitality environments shape volume patterns, specification requirements, and procurement cycles, allowing teams to tailor product development and sales motions to distinct buyer behaviors.
- Regional revenue distribution that highlights where market activity concentrates and where growth corridors are emerging, supporting decisions around distribution strategy, localization, and cross-border sourcing exposure.
- Competitive benchmarking and concentration metrics that quantify market clOUT and identify the structural conditions under which scale advantages translate into share gains versus circumstances where agility and specialization create outsized returns.
Each analytical layer is constructed to be modular, allowing strategy, finance, procurement, and commercial teams to extract the specific inputs required for their planning cycles without wading through undifferentiated commentary.
Dynamics Reshaping the Playing Field
No market strategy is complete without a clear understanding of the forces that will compress margins, alter sourcing economics, or redirect demand. Several macro and regulatory developments are already reshaping the wood furniture landscape, and their effects will compound through the forecast window.
Trade Policy and Tariff Escalation
The regulatory environment for wood and wood-derived products has tightened considerably. A U.S. presidential proclamation imposed a 10 percent ad valorem tariff on softwood timber and lumber imports, alongside a 25 percent tariff on upholstered wooden products and kitchen cabinets/vanities, effective October 14, 2025. Those rates are scheduled to increase to 30 percent and 50 percent respectively on January 1, 2026. In parallel, the U.S. Commerce Department raised antidumping and countervailing duties on Canadian softwood lumber imports to 35 percent in 2025, layered on top of the existing 10 percent Section 232 tariff, which collectively pushed overall Canadian lumber prices higher by approximately 45 percent.
These shifts alter the cost calculus for manufacturers and importers that depend on cross-border timber flows. They create pressure on product costing, encourage material substitution evaluation, and raise the strategic importance of supply chain diversification. Companies that rely on a narrow set of origin points face heightened exposure, while those with flexible sourcing architectures and hedged inventory strategies are better positioned to preserve margin integrity.
Traceability and Compliance in the European Market
On the other side of the Atlantic, the EU Deforestation Regulation introduces a new compliance threshold. Effective December 30, 2025, the regulation requires full traceability and due diligence for all timber and timber products placed on the EU market. For furniture exporters and multinational supply chains, this means documentation rigor, origin verification, and supplier audits become non-negotiable operational requirements rather than optional best practices.
Compliance is not merely a legal checkbox. It affects time-to-market, supplier qualification cycles, and the cost structure of European-facing product lines. Organizations that embed traceability into their sourcing and manufacturing workflows early will reduce friction as enforcement intensifies; those that delay will face rework, shipment delays, and potential market access constraints.
Raw Material Baselines and Supply Continuity
Underlying these policy dynamics is the physical supply of wood fiber. U.S. softwood lumber production reached 63.578 million cubic meters in 2023, forming the primary raw material foundation for a broad swath of wood furniture production. Production levels, harvesting patterns, and mill capacity interact with transport costs, millgate pricing, and inventory behavior to determine the cost environment facing furniture manufacturers.
Strategic sourcing in this context requires more than contract negotiation. It demands visibility into harvest schedules, regional mill performance, substitute material performance characteristics, and the lead-time implications of tariff-induced reorder behavior. The report maps these raw material interactions to furniture production economics, helping procurement and operations teams anticipate rather than react to cost movement.
Competitive Landscape: Scale, Specialization, and Strategic Postures
The competitive architecture of the wood furniture market is characterized by a mix of broad-scale manufacturers, office and residential specialists, and craftsmanship-oriented brands that compete on material provenance, design distinctiveness, and sustainability narratives. Concentration metrics indicate a market where the top three competitors account for approximately 23.5 percent of revenue and the top five reach approximately 31.5 percent, suggesting that while scale players hold meaningful position, a substantial share of activity resides with mid-tier and niche operators.
This dispersion creates a multi-front competitive environment. Large manufacturers leverage distribution breadth, product breadth, and purchasing scale, while specialized producers compete through design language, material integrity, and localized or curated value propositions. The strategic implication is clear: competitive advantage is no longer a function of scale alone. It is increasingly determined by how effectively a company aligns its sourcing model, product architecture, and channel strategy with the specific demands of its target segment.
Scale and Broad Portfolio Players
Ashley Furniture Industries, headquartered in Arcadia, Wisconsin, operates as a mass-market residential wood furniture manufacturer and retailer with extensive collections spanning solid and engineered wood case goods, tables, beds, and upholstered pieces. Its scale and breadth position it to capture volume across multiple residential subcategories, while its retail and distribution footprint supports broad consumer reach.
HNI Corporation, based in Muscatine, Iowa, manufactures office and residential wood furniture including desks, chairs, and case goods, with a particular emphasis on wood-based products. Its dual focus across workplace and home environments gives it flexibility to balance demand cycles between commercial specification and residential consumption.
Haworth Inc., headquartered in Holland, Michigan, designs and manufactures wood office furniture including tables, desks, and storage solutions. Its concentration in the office segment aligns with institutional procurement cycles and workplace design trends, where specification quality, durability, and configuration flexibility matter as much as cost.
La-Z-Boy Incorporated, located in Monroe, Michigan, produces upholstered and wood furniture lines including bedroom, dining, and occasional wood pieces. Its heritage in comfort-oriented residential seating, combined with wood-based offerings, positions it at the intersection of style, function, and recurring replacement demand.
Craft, Material Integrity, and Sustainability-Led Positioning
On the other side of the competitive spectrum, a set of manufacturers competes through material provenance, craftsmanship, and sustainability narratives that appeal to buyers prioritizing durability, aesthetics, and responsible sourcing.
Stickley, based in Upstate New York, specializes in American-made solid wood furniture with Mission and modern designs for living, dining, and bedroom applications. Its design language and domestic manufacturing identity support a premium positioning that relies on authenticity and durability rather than volume alone.
Whittier Wood Furniture, a U.S.-based family-owned producer, focuses on heritage real wood bedroom, dining, and living room furniture using American hardwoods. Its ownership structure and material emphasis align with consumers who value long-life products and recognizable craftsmanship.
Vermont Woods Studios, headquartered in Johnson, Vermont, produces handcrafted solid wood furniture using North American sustainably sourced hardwoods for residential tables, beds, and seating. Its sustainability-forward sourcing and craftsmanship positioning are particularly relevant as traceability expectations rise and buyers scrutinize origin claims.
Arista Wood, formerly known as Urban Barnwood Furniture and based in Sugarcreek, Ohio, manufactures reclaimed barnwood and fine hardwood furniture including dining sets, beds, and cabinets with a sustainable focus. In February 2026, the company completed a rebranding to broaden its focus on reclaimed barnwood and fine hardwood furniture lines, signaling a deliberate shift in market positioning and product storytelling.
Furnirem, with U.S. operations rooted in Türkiye, specializes in handcrafted solid wood furniture, including dining table sets, coffee tables, and living room collections using oak, walnut, and pine. In March 2026, the company announced an expansion of its dining table sets and coffee table collections, introducing new leg styles, wood finish options, shapes, sizes, nesting designs, and storage-integrated features tailored to urban living. This move illustrates how product-line expansion can respond directly to spatial constraints and lifestyle-driven demand in dense residential markets.
Together, these players illustrate a competitive environment where a few broad-scale manufacturers anchor volume, while a diverse set of specialists competes on design, material integrity, and sustainability. The report maps these postures to segment-level opportunity, helping companies understand where differentiation is sustainable and where price competition is likely to intensify.
Segment-Level Strategic Implications
Beyond competitive profiles, the study examines how product type, application, and region interact to shape revenue composition and growth potential. While headline figures provide orientation, the actionable insights emerge from the way these layers intersect.
At the type level, the analysis distinguishes between solid wood furniture, wood-based panel furniture, and miscellaneous furniture categories. Each carries different manufacturing economics, material sourcing requirements, and end-user perception profiles. Solid wood offerings often command different price and longevity expectations, while wood-based panel constructions can support cost efficiency and design flexibility in specific applications. The report evaluates how these categories contribute to overall revenue mix and where product development investment is most likely to generate differentiated returns.
At the application level, the study explores how home furniture, office furniture, and commercial and hospitality environments drive distinct procurement behaviors, specification criteria, and replacement cycles. Home demand is shaped by residential consumption patterns, space constraints, and aesthetic preferences; office demand is influenced by workplace design standards, procurement cycles, and durability requirements; commercial and hospitality demand responds to brand experience, throughput, and design coherence. Understanding these distinctions allows companies to align product development, channel strategy, and sales messaging with the expectations of each environment.
Regionally, the report identifies where revenue concentrates and where growth momentum is building, without reducing the analysis to a simple ranking. Instead, it examines the supply-demand balance, channel maturity, tariff exposure, and regulatory context that shape regional opportunity. This regional framing is particularly important given the uneven impact of trade policy and traceability requirements across markets, which means that a strategy optimized for one geography may not translate directly to another.
Why This Study Matters for 2026 Planning
As enterprises move into 2026 planning cycles, the wood furniture market presents a series of interdependent decisions: how to structure sourcing in a tariff-affected environment, how to balance solid wood and panel-based product development, how to position for traceability compliance in key export markets, and how to allocate commercial resources across home, office, and hospitality applications. Each decision depends on a clear view of where volume sits, where margins are defended, and where competitive intensity is likely to rise.
This report is built to support those decisions with defensible, forward-looking analysis. It connects macro trajectory to segment-level opportunity, embeds regulatory and raw material dynamics into the growth narrative, and positions competitive profiles within a framework that clarifies where scale, specialization, and compliance capability create advantage. The result is a practical reference point for board-level strategy, capital allocation, and operational planning.
Access the Full Intelligence Package
The overview presented here is designed to demonstrate the analytical depth and strategic relevance of the study, while preserving the detailed segment data, regional revenue breakdowns, and competitive metrics that executives need for precise planning. To access the complete market size trajectory, segmentation splits, concentration analysis, company benchmarking, and forecast scenarios, request the full Wood Furniture Market report.
For strategy, finance, procurement, and commercial leaders seeking a clear basis for 2026 decisions and a disciplined view of the 2026–2032 outlook, the full study provides the structured intelligence required to move from assumption to evidence-based action.
For detailed analysis of this topic, please visit the official page: Wood Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Model Based Enterprise Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
Between 2020 and 2035, the Asia-Pacific Model Based Enterprise market is expected to expand from USD 2,100 Million in 2020 to nearly USD 13,800 Million by 2035, representing accelerated adoption of digital transformation strategies and integration of advanced technologies. The market size reached USD 5,400 Million in 2025 and is projected to maintain a double-digit CAGR through 2035. This dynamic growth is fueled by the proliferation of smart factories, rapid deployment of digital twin platforms, and increasing government support for digital infrastructure. The ongoing digital shift across diverse industrial verticals will continue driving revenue increments year-over-year.
Read More - https://bussinessinsights.com/research-report/asia-pacific-model-based-enterprise-market
Among applications, Manufacturing accounts for 38% of the Asia-Pacific MBE market by 2025 as organizations prioritize digitalization of shop-floor operations and predictive analysis for improved yield. Product Design forms 29% of the market, reflecting the region’s focus on front-end digitalization and simulation-driven engineering. Quality Inspection, Supply Chain Management, and Maintenance collectively make up 33%, highlighting the growing deployment of digital twins and AI for QA and logistics optimization. The dominance of manufacturing and product design segments underscores the MBE market's critical role in reducing time-to-market, ensuring product reliability, and supporting connected, agile manufacturing ecosystems across APAC.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-model-based-enterprise-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Model Based Enterprise Market industry?
The top five players in the Asia-Pacific Model Based Enterprise market are Siemens AG, Dassault Systèmes, Autodesk Inc., PTC Inc., and Hexagon AB. These companies drive innovation by providing advanced software solutions, digitalization tools, and industry-specific applications, serving sectors such as aerospace, automotive, and manufacturing.
What is the Asia-Pacific Model Based Enterprise Market growth?
The Asia-Pacific Model Based Enterprise Market is experiencing rapid growth, with a CAGR exceeding 15% in recent years. For instance, Siemens reported significant adoption of its digital twin technologies in 2023, with increased investments from major manufacturing firms across China, Japan, and South Korea.
Which segment accounted for the largest Asia-Pacific Model Based Enterprise Market share?
The automotive and aerospace applications segment holds the largest share in the Asia-Pacific Model Based Enterprise Market. Companies like Dassault Systèmes and Autodesk have seen widespread use of their model-based solutions to streamline component design, improve collaboration, and accelerate time-to-market in these industries.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Ethernet Storage Fabric Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific Ethernet Storage Fabric Market is projected to witness strong and steady revenue growth from 2020 to 2035. From an estimated USD 1,765 Million in 2025, the market is forecasted to achieve a substantial increase to around USD 5,740 Million by 2035, reflecting rising adoption in data-centric industries. Expanding digital infrastructure, regulatory mandates, and relentless innovation from key market players contribute to this upward revenue trajectory, solidifying APAC as a pivotal growth region.
Read More - https://bussinessinsights.com/research-report/asia-pacific-ethernet-storage-fabric-market
Enterprise Data Centers dominate the Asia-Pacific Ethernet Storage Fabric Market by application in 2025, reflecting widespread digitalization and the need for robust, low-latency data environments. Cloud Service Providers follow closely, leveraging fabric technologies for scalable, secure storage. Increasing investments in IT modernization further drive adoption in telecommunications, BFSI, government, and healthcare, marking these as emerging segments with high growth potential as storage needs diversify.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-ethernet-storage-fabric-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Ethernet Storage Fabric Market industry?
The top five players in the Asia-Pacific Ethernet Storage Fabric Market are Cisco Systems, Huawei Technologies, Juniper Networks, Dell Technologies, and Broadcom Inc. These companies are recognized for their advanced networking solutions, strong market presence, innovation in Ethernet fabric technologies, and expanding regional operations across the Asia-Pacific.
What is the Asia-Pacific Ethernet Storage Fabric Market growth?
The Asia-Pacific Ethernet Storage Fabric Market has seen significant growth, driven by increased adoption of cloud services and data centers. For instance, in 2023, Huawei Technologies expanded its offerings, resulting in accelerated market adoption. The market is expected to maintain a robust CAGR through 2028, reflecting ongoing regional digitalization.
Which segment accounted for the largest Asia-Pacific Ethernet Storage Fabric Market share?
The data center segment accounted for the largest market share in the Asia-Pacific Ethernet Storage Fabric Market. This dominance is due to the rapid proliferation of hyperscale and enterprise data centers in countries like China, India, and Singapore, driven by demanding storage and data processing requirements.
Thanks & Regards,
Priya
sales@bussinessinsights.com
The Asia-Pacific eSIM market is experiencing a strong growth trajectory, with revenues growing from approximately USD 920 Million in 2020 to a projected USD 2,700 Million in 2025, and estimated to reach USD 14,800 Million by 2035. This rapid expansion is fueled by robust adoption across consumer electronics, automotive, and industrial IoT verticals. The proliferation of 5G and government initiatives to promote smart connectivity further support this upward trend. China, India, and Japan are key contributors, with accelerated integration across multiple application segments and a thriving ecosystem of device manufacturers and network providers.
Read More - https://bussinessinsights.com/research-report/asia-pacific-esim-market
Smartphones remain the leading application for eSIM in the Asia-Pacific region, driven by strong consumer demand and manufacturers’ broad integration strategies. Wearables are gaining traction, supported by health-centric trends and compatibility with premium smartwatches. Connected cars, benefitting from the region’s accelerating EV push, are seeing a sharp rise in eSIM adoption, particularly in China and Japan. Industrial devices, tablets, and laptops show steady growth, but remain behind consumer-led applications. As eSIMs become more accessible via network operator and manufacturer ecosystems, the mix is expected to further diversify beyond smartphones in the coming years.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-esim-market
Frequently Asked Questions
Who are the key players in Asia-Pacific eSIM Market industry?
Key players in the Asia-Pacific eSIM market include Thales Group, Giesecke+Devrient, Infineon Technologies AG, STMicroelectronics, and NXP Semiconductors. These companies are forefront innovators, providing robust eSIM solutions that enable secure connectivity for IoT devices, smartphones, and automotive sectors in the growing digital landscape.
What is the Asia-Pacific eSIM Market growth?
The Asia-Pacific eSIM market is witnessing rapid growth, with an estimated CAGR of over 15% from 2023 to 2028. Increased adoption of eSIM technology in smartphones by companies such as Samsung is driving this growth, alongside expansion in IoT and connected car initiatives.
Which segment accounted for the largest Asia-Pacific eSIM Market share?
Consumer electronics, especially smartphones, accounted for the largest market share in the Asia-Pacific eSIM market. The sector's dominance is attributed to the proliferation of eSIM-enabled devices from leading manufacturers like Apple and Samsung, meeting consumers' demand for flexible and convenient connectivity solutions.
Thanks & Regards,
Priya
sales@bussinessinsights.com
Asia-Pacific Terahertz Technology Market Size, Share & Forecast Report, 2034
By priyaRaut, 2026-09-07
The Asia-Pacific Terahertz Technology market has demonstrated strong revenue growth from 2020 to 2035. Starting at approximately $320 million in 2020, the market reached $650 million in 2025 and is forecasted to exceed $2,100 million by 2035. This significant upward trajectory underscores the technology's growing integration across industries, supported by advancements in terahertz-based imaging, spectroscopy, and wireless communication systems. The market benefits from an expanding applications base and ongoing R&D fostered by public-private partnerships in key Asia-Pacific economies.
Read More - https://bussinessinsights.com/research-report/asia-pacific-terahertz-technology-market
Medical & Healthcare is the leading application for terahertz technology in Asia-Pacific in 2025, representing the most significant market share. This dominance is propelled by rising investment in non-invasive diagnostic tools and cancer detection solutions. Security & Surveillance is the second-largest segment, driven by heightened airport and border security needs. Non-destructive Testing follows, benefiting from higher adoption in quality assurance across manufacturing sectors. The balanced distribution showcases how terahertz technology underpins vital sectors focusing on well-being, safety, and industrial productivity.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/asia-pacific-terahertz-technology-market
Frequently Asked Questions
Who are the key players in Asia-Pacific Terahertz Technology Market industry?
Key players include TeraView, Advantest Corporation, TeraSense Group Inc., Menlo Systems GmbH, and Nippon Telegraph & Telephone Corporation (NTT). These companies are pioneers in terahertz solutions, specializing in imaging, spectroscopy, and communication systems for applications in security, healthcare, and industrial inspection across the Asia-Pacific region.
What is the Asia-Pacific Terahertz Technology Market growth?
The Asia-Pacific Terahertz Technology Market is experiencing robust growth, driven by increased adoption in non-destructive testing and medical imaging. For example, Advantest Corporation reported a notable rise in sales due to surging demand for terahertz-based quality inspection systems in semiconductor manufacturing during 2023.
Which segment accounted for the largest Asia-Pacific Terahertz Technology Market share?
Imaging applications account for the largest market share in the Asia-Pacific Terahertz Technology Market. Driven by expanding use in security screening at airports, material characterization, and medical diagnostics, imaging systems remain highly adopted, especially in countries such as Japan and China.
Thanks & Regards,
Priya
sales@bussinessinsights.com
PW Consulting: Alumina Zirconia Oxide Abrasives Market Hits $307M in 2025, Projects 5.2% CAGR to 2032
By PW Consulting, 2026-09-07
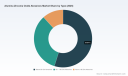
Navigating the Alumina Zirconia Oxide Abrasives Market: Strategic Imperatives for 2026 and Beyond
Executive Summary: The Case for Deep-Dive Intelligence
The global abrasives industry stands at a critical inflection point. As manufacturing processes become increasingly precision-driven and sustainability mandates tighten, the demand for high-performance refractory grains—specifically Alumina Zirconia Oxide abrasives—has evolved from a commodity consideration to a strategic differentiator. For executives, procurement leaders, and investors operating in 2026, understanding the trajectory of this market is not merely about tracking price fluctuations; it is about anticipating supply chain resilience, technological substitution, and competitive consolidation.
High-performance lubricants for Semiconductor Market
PW Consulting's latest comprehensive study, Alumina Zirconia Oxide Abrasives Market, offers a granular view of this landscape. This article serves as a strategic preview, outlining the macro-economic drivers, competitive tensions, and regulatory headwinds identified in our full report. Our goal is to demonstrate why relying on surface-level data is insufficient for navigating the forecast period of 2026 through 2032.
PEEK for Semiconductor FOUP Market
Market Trajectory: From Recovery to Structural Growth
The market has demonstrated remarkable resilience over the past half-decade. Analysis of historical data from 2020 through 2025 reveals a consistent upward trajectory, recovering swiftly from early pandemic-era disruptions. The global revenue base, measured in USD millions, has expanded steadily, positioning the industry for a robust forecast period. Our models project the market size to reach approximately 324.75 million in 2026, escalating to over 436.18 million by 2032.
Crude Oil to Chemicals Market
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 5.2 percent. While this figure might appear moderate at first glance, it represents significant value creation in a mature industrial sector. The growth is not uniform across all vectors; it is driven by specific shifts in material science requirements and regional industrial output. Decision-makers must understand that this aggregate growth hides divergent performance across product grades and application segments, which are detailed exclusively in the full dataset.
- Historical Stability: The market matured significantly between 2020 and 2025, stabilizing at a base value of 307.0 million in the base year.
- Forecast Momentum: The projected jump to 390.28 million by 2030 suggests a sustained demand cycle, particularly in high-performance coating and bonding applications.
- Long-term Horizon: Extended forecasts to 2032 indicate continued expansion, suggesting that investment cycles aligned with this timeline will capture the bulk of value generation.
Segmentation Dynamics: Product Grades and Application Vectors
Success in this market requires a nuanced understanding of grit sizes and application formats. The market is not monolithic; it is stratified by the fineness of the abrasive grain and the manner in which it is deployed. Our research categorizes the market into three primary grit segments: Below 60 Grit, 60–180 Grit, and Above 180 Grit. Each segment serves distinct industrial needs, ranging from heavy-duty material removal to precision surface finishing.
Similarly, the application landscape is divided into Consolidated Abrasives, Coated Abrasives, and others. The balance between these segments dictates inventory strategy and R&D focus for manufacturers. For instance, the shift towards coated abrasives in automotive refinishing versus consolidated abrasives in steel mill maintenance requires different logistical and technical approaches.
In the full report, we provide exact revenue splits and volume contributions for each segment. Accessing this level of detail is crucial for companies looking to allocate capital efficiently. Without knowing which grit size or application type is driving the majority of the 5.2 percent CAGR, strategic bets risk being misaligned with market reality.
- Grit Stratification: Understanding the revenue contribution of coarse versus fine grains is essential for production planning.
- Application Mix: The ratio of consolidated to coated abrasives varies significantly by region and end-user industry.
- Value Concentration: Higher grit and specialized applications often command higher margins, influencing total market valuation.
Competitive Landscape: The Big Players and Emerging Challengers
The market structure is characterized by high concentration. Our analysis indicates a CR3 and CR5 of 80.0 percent, signaling that a handful of key players dominate the landscape. This oligopolistic structure has profound implications for pricing power, supply security, and innovation speed. In 2026, navigating this landscape requires knowing not just who the players are, but how their specific strategic moves impact your supply chain.
Saint-Gobain remains a titan in this space, headquartered in Paris, France. They are the primary producer of fused alumina-zirconia abrasive grains, including notable grades like Norzon NV 40% AZ and MCA 1360. Their strategic focus has shifted towards sustainability with the launch of their Lumeos™ premium grades. In July 2025, they launched the Lumeos™ family featuring AZ25L, utilizing recycled raw materials as part of a broader sustainability roadmap. For buyers, this signals a potential shift in material sourcing requirements and premium product availability.
3M Company , based in St. Paul, Minnesota, continues to innovate beyond traditional grains. They are currently manufacturing Precision-Shaped Grain abrasives that reportedly outperform standard alumina zirconia and ceramic in longevity for metalworking discs and wheels. This represents a technological substitution threat that traditional producers must monitor closely.
On the other side of the spectrum, Luoyang HongFeng Abrasives Co., Ltd. in Luoyang, Henan, China, represents the dedicated capacity emerging from Asia. They produce AZ25, AZ40, and composite grains from bauxite and zirconia fusion. Their participation at IPTEX GRINDEX 2026 in November 2025 highlighted a strong emphasis on precision grinding and surface finishing, indicating a push into higher-value segments traditionally dominated by Western firms.
Finally, Tyrolit Schleifmittelwerke Swarovski AG & Co. KG from Austria supplies zirconia alumina grains for premium bonded abrasives, including saw gumming wheels and cut-off tools. Their focus on premium bonded applications underscores the segmentation between high-volume commodity grinding and specialized tool manufacturing.
- Consolidation Risk: With 80 percent of the market controlled by the top players, supply chain diversification is a critical risk mitigation strategy.
- Innovation Arms Race: Competitors like 3M and Saint-Gobain are actively developing grains that extend product life, altering total cost of ownership calculations for end-users.
- Regional Capacity Shifts: New capacity in Asia and product launches in Europe suggest a shifting balance of power in manufacturing hubs.
Raw Material Volatility and Regulatory Pressures
No market analysis is complete without examining the input costs and regulatory environment. In 2025, the reported quantity of bauxite consumed was estimated at 1.7 million tons, a 4 percent increase from 2024, with an estimated value of 54 million. However, cost and availability are not the only factors. Silicon carbide and alumina zirconia can substitute for alumina and bauxite in abrasives, but they come at a higher cost. This substitution dynamic creates a price floor and volatility risk that directly impacts margin projections.
Furthermore, regulatory and infrastructure constraints in key markets like the United States are tightening. US alumina refinery production in 2025 showed one domestic refinery operating with a 500,000-ton-per-year facility remaining idle since 2020. Meanwhile, average U.S. import prices for crude dry bauxite and metallurgical rose 4 percent and 9 percent respectively from 2024. These figures from the USGS indicate a tightening supply chain that could exacerbate cost pressures moving into 2026.
The full report delves into how these raw material fluctuations correlate with regional pricing structures and how companies can hedge against these volatilities through strategic sourcing or vertical integration.
- Input Cost Sensitivity: Bauxite consumption trends directly influence production costs for alumina-based abrasives.
- Substitution Economics: The cost premium of silicon carbide and alumina zirconia versus standard alumina affects margin structures.
- Infrastructure Bottlenecks: Idle refinery capacity and rising import prices suggest potential supply constraints in North America.
Why This Report is Essential for 2026 Decision-Making
In an environment defined by high market concentration and raw material volatility, generic industry news is insufficient for strategic planning. The Alumina Zirconia Oxide Abrasives Market report provides the actionable intelligence required to make informed decisions. Whether you are evaluating potential acquisition targets, optimizing your procurement mix, or forecasting revenue based on regional growth, you need access to the specific data points that drive these conclusions.
The report goes beyond macro trends to offer company profiles, recent development timelines, and segmentation splits that allow for precise scenario planning. For example, knowing exactly how much revenue is attributed to Coated Abrasives versus Consolidated Abrasives allows a company to pivot its sales force training or marketing spend effectively. Similarly, understanding the specific contributions of the Asia Pacific region versus Europe helps in balancing geographic risk.
We intentionally withhold the specific percentage splits and detailed regional revenue figures in this summary to encourage a deep dive into the full dataset. These numbers are critical for building accurate financial models and cannot be approximated without loss of fidelity.
Conclusion: Securing Your Strategic Position
The period from 2026 to 2032 promises to be transformative for the abrasives industry. With a clear growth trajectory towards 436.18 million and a competitive landscape dominated by innovators focused on sustainability and precision, the window for strategic adjustment is now. Companies that rely on outdated assumptions about bauxite availability or market concentration risk being outmaneuvered by competitors with superior intelligence.
PW Consulting invites you to access the full Alumina Zirconia Oxide Abrasives Market study. The complete report contains the detailed segmentation data, regional analysis, and comprehensive company profiles necessary to navigate this complex market. Do not leave your 2026 strategy to chance. Equip your team with the precise data needed to thrive in a consolidated, high-performance market environment.
For detailed analysis of this topic, please visit the official page: Alumina Zirconia Oxide Abrasives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Light Switch & Socket Market Hits $96.4M in 2025, Set for 4.2% CAGR Through 2032
By PW Consulting, 2026-09-07
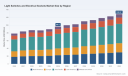
Strategic Intelligence for 2026: Navigating the Light Switches and Electrical Sockets Market
The global electrical infrastructure sector stands at a critical inflection point. As we move through 2026, decision-makers across real estate development, construction management, and electrical manufacturing require more than historical hindsight. They need forward-looking intelligence that accounts for shifting consumer preferences, evolving safety regulations, and the rapid integration of smart connectivity into standard wiring devices. PW Consulting's latest market research on the Light Switches and Electrical Sockets Market is designed to meet this exact need, providing a comprehensive framework for strategic planning over the next seven years.
NFC Temperature Indicator Market
This industry has demonstrated remarkable resilience and steady expansion over the past half-decade. From a baseline of 78.48 billion USD in 2020, the market has navigated supply chain disruptions, inflationary pressures, and regional construction slowdowns to reach an estimated 96.4 billion USD by 2025. The trajectory ahead suggests continued momentum, with the market expected to expand to 99.94 billion USD in 2026 and accelerate toward 128.57 billion USD by 2032. This compound annual growth rate of 4.2 percent reflects not merely population growth or replacement cycles, but a structural transformation in how buildings are powered, controlled, and integrated into broader energy ecosystems.
Galactomannan (GM) Market
Why This Research Matters for 2026 Decision-Making
Enterprise strategy in the electrical accessories space has historically relied on lagging indicators. Sales figures from the previous quarter, backlog reports, and regional distributor feedback provide necessary but insufficient signals for capital allocation, product portfolio optimization, and market entry timing. The 2026-2032 forecast window demands a different approach. Organizations must anticipate regulatory shifts, evaluate the pace of smart home adoption across residential and commercial segments, and understand the competitive intensity that defines pricing power and margin sustainability.
Hydrogen Sulfide Capture and Removal Technologies Market
PW Consulting's comprehensive analysis delivers exactly this forward-looking perspective. The report maps the market from historical baselines through the forecast period, enabling executives to calibrate investment cycles against anticipated demand surges. Whether your organization operates in manufacturing, distribution, contract electrical supply, or real estate development, the strategic value lies in identifying which segments will generate disproportionate growth, which regions will experience infrastructure-led expansion, and which competitive dynamics will compress or expand profitability.
Crucially, the research does not treat the market as a monolith. By disaggregating demand drivers, application-specific consumption patterns, and regional growth differentials, the analysis equips leadership teams with the granularity required to allocate resources efficiently. The report's structure ensures that readers can trace how macro-level market size evolution connects to micro-level tactical decisions, from SKU portfolio rationalization to targeted geographic expansion.
Market Architecture and Segmentation Dynamics
Understanding the shape of the market requires examining how revenue flows across product categories, end-use applications, and geographic corridors. The data reveals a market where certain segments command disproportionate share, while others present higher-growth opportunities that may require strategic repositioning to capture.
Product Category Distribution
The portfolio landscape divides between light switches and electrical sockets, with switches representing the larger revenue contributor. This structural imbalance reflects the broader range of aesthetic, functional, and smart-control variations available in the switch category, as well as higher replacement frequency in renovation and interior upgrade cycles. Sockets, while a smaller share of total revenue, benefit from standardized demand in new construction and strict compliance requirements that reduce volatility. The interplay between these two categories matters for manufacturers and distributors alike, as portfolio composition influences inventory strategy, channel negotiation leverage, and margin profiles.
Application-Driven Demand
End-use segmentation reveals where consumption intensity concentrates. Residential applications dominate the demand profile, driven by new housing starts, renovation activity, and the ongoing retrofit of legacy electrical infrastructure with modern, code-compliant devices. Commercial applications represent a substantial secondary channel, with office buildings, retail spaces, and hospitality projects generating consistent procurement cycles. Industrial applications, while smaller in relative terms, often deliver higher unit volumes per project and demand specialized durability, grounding, and safety features that differentiate product specifications from mainstream residential and commercial lines. Understanding the mix across these three application layers is essential for anyone evaluating channel partnerships, production capacity allocation, or sales force deployment.
Regional Growth Corridors
Geographic demand is distributed across five major regions, with Asia Pacific commanding the largest share of market revenue. This concentration aligns with sustained urbanization, large-scale residential and infrastructure projects, and the rapid expansion of middle-income households upgrading electrical installations. North America maintains a significant position, supported by renovation activity, code-driven replacement cycles, and a mature smart home adoption curve. Europe reflects a more regulation-intensive environment where energy efficiency standards and building electrification policies shape procurement behavior. Latin America and the Middle East and Africa collectively represent emerging but strategically important corridors, where infrastructure investment programs and urban development initiatives progressively expand addressable demand. The report provides the comparative framework needed to evaluate which regional dynamics align with your organization's capabilities and risk tolerance.
Competitive Landscape and Strategic Positioning
The light switches and electrical sockets market is characterized by a concentrated competitive structure, with the top three players accounting for 38.0 percent of market revenue and the top five collectively commanding 55.0 percent. This concentration does not imply a static hierarchy; rather, it reflects the scale advantages, brand equity, and distribution network depth that established players have accumulated. Yet the remaining market share is distributed across a diverse set of regional specialists, premium boutique manufacturers, and cost-focused producers, creating a landscape where differentiation strategies can still yield meaningful share gains.
Global Leaders and Portfolio Strategies
Several multinational corporations anchor the competitive framework. Schneider Electric, headquartered in France, maintains a leadership position through its Wiring Devices division, offering integrated smart-connected ranges under brands such as Merten, Clipsal, Odace, and X Series. The company's strategy emphasizes design differentiation, connectivity integration, and global scale, positioning it to capture demand from premium residential projects and commercial build-outs seeking unified electrical ecosystems.
Legrand, also based in France, brings a specialist focus on electrical infrastructure with a multi-brand architecture encompassing Legrand, Bticino, Pass & Seymour, and Vantage. This portfolio breadth enables the company to address residential, commercial, and smart switch and socket requirements across varied market segments. In a recent strategic move, Legrand released a comprehensive wiring device catalog that consolidates its industry-leading portfolio into a single reference guide, signaling a clear intent to streamline specification processes for architects, contractors, and distributors.
Siemens AG, operating from Germany, provides DELTA switch and socket ranges with particular strength in commercial, industrial, and building automation applications. Its positioning aligns with projects that demand integration with broader automation systems, where socket and switch hardware functions as part of a controlled environment rather than a standalone accessory. ABB Ltd, based in Switzerland, contributes modern wiring accessories spanning light switches, sockets, and smart ranges for residential, commercial, and industrial contexts, leveraging its global presence to serve diverse specification requirements.
Eaton Corporation, headquartered in Ireland, supplies wiring devices and connectivity solutions including switches, receptacles, and modular hospital-grade products, reflecting an emphasis on reliability-critical environments. Leviton Manufacturing Co., Inc., based in the United States, manufactures lighting controls, switches, dimmers, outlets, and smart home wiring devices, maintaining a strong North American footprint and a growing presence in connected home applications. Hubbell Incorporated, also US-based, provides electrical wiring devices, switches, and sockets with a focus on commercial and industrial applications, where durability and compliance specifications carry heightened importance.
Regional Specialists and Niche Positioning
Beyond the multinational core, regional specialists play an increasingly visible role. Lider Electric, operating from California, manufactures premium light switches, dimmers, multi-standard power sockets, modular faceplates, and USB charging solutions, addressing demand for aesthetic customization and convenience features in upscale residential and hospitality markets. Panasonic Corporation, headquartered in Japan, offers consumer and smart light switches, electrical sockets, and energy-efficient wiring devices, including the Anchor brand in select markets, combining consumer electronics credibility with electrical hardware expertise. Havells India Ltd, based in Gurgaon, supplies affordable light switches, electrical sockets, and smart home electrical solutions for residential and commercial use, reflecting the growth dynamics of price-sensitive but volume-rich markets where accessibility and functionality must be carefully balanced.
The competitive implications are clear. Market share leadership provides distribution leverage, procurement scale, and brand recognition, but it also invites scrutiny on pricing and margin performance. Organizations that differentiate through smart connectivity, design-led product architecture, or application-specific reliability can command premium positioning even within a concentrated market. The report's competitive profiling section provides the detailed benchmarking required to evaluate where your organization's capabilities align with market opportunities and where gaps demand strategic investment.
Regulatory Environment and Technical Standards
The market does not operate in a regulatory vacuum. Electrical infrastructure is governed by safety codes, dimensional standards, and evolving technical specifications that shape product design, testing requirements, and installation practices. Two recent developments illustrate the kinds of changes that influence 2026 planning cycles.
The 2026 edition of the National Electrical Code (NEC) introduces new articles addressing electrical installations operating over 1000 volts ac and 1500 volts dc, alongside a reorganization of Chapters 1 through 7. While high-voltage provisions may appear distant from the everyday light switch and socket market, the broader reorganization signals a comprehensive update to installation practices, grounding requirements, and safety protocols that can cascade into product certification timelines and specification language for connected systems within larger electrical infrastructure projects.
Simultaneously, the ANSI/NEMA WD 00006-2026 technical revision addresses wiring devices through updated dimensional specifications. Standardization of physical dimensions matters profoundly for manufacturers and distributors, as it influences compatibility with existing faceplate systems, enclosure fitments, and installation workflows. Any revision to dimensional standards can affect product redesign schedules, inventory transition planning, and the competitive balance between incumbents with established dimensional architectures and new entrants seeking to introduce differentiated form factors.
These regulatory and standards developments are not isolated events; they are part of a broader pattern in which safety, interoperability, and energy efficiency increasingly shape procurement criteria. The market research incorporates these dynamics into its forward-looking analysis, helping organizations anticipate compliance costs, specification shifts, and the timing of product updates required to maintain market access.
Strategic Applications of the Research
PW Consulting's Light Switches and Electrical Sockets Market research is structured to translate data into actionable strategy. The report goes beyond aggregate figures to provide the operational detail that executives, planners, and analysts need when forming 2026 and beyond investment decisions.
The analysis covers historical market size evolution from 2020 through the base year of 2025, establishing a reliable trajectory against which forecast assumptions can be validated. It then projects market size through 2032, providing a seven-year planning horizon that aligns with typical capital budgeting cycles, product development lead times, and regional expansion roadmaps. This temporal scope allows organizations to model multiple scenarios, test sensitivity to growth rate variations, and identify inflection points where demand acceleration or deceleration may require strategic pivots.
Segmentation analysis is presented with sufficient depth to support portfolio and channel decisions without overwhelming readers with unnecessary granularity. By examining the interplay between product type, application, and region, the report reveals where concentration creates stability and where dispersion offers growth optionality. Competitive profiling extends beyond basic company descriptions to provide context on brand portfolios, application focus, geographic presence, and recent strategic moves that signal future direction. This enables readers to benchmark their own positioning and identify potential partnership, acquisition, or competitive response pathways.
The research also integrates industry context, including regulatory updates and standards revisions, into its market dynamics assessment. This ensures that strategic recommendations are grounded not only in demand forecasts but also in the compliance and technical realities that shape product design, certification, and market entry timing. For organizations operating across multiple jurisdictions, the ability to anticipate regulatory divergence and standardization trends is a material competitive advantage.
What Decision-Makers Will Gain
Access to this comprehensive market intelligence delivers several concrete benefits for organizations operating in or adjacent to the light switches and electrical sockets sector. Leadership teams can align product development pipelines with anticipated demand patterns, reducing the risk of launching into segments where growth is plateauing. Sales and distribution leaders can prioritize channel investments in regions and application categories where revenue expansion is most probable, improving return on commercial infrastructure spend. Procurement and supply chain planners can calibrate inventory strategies against forecast visibility, balancing the cost of holding stock against the risk of stockouts in high-growth corridors.
For competitive strategy functions, the report provides the benchmarking detail required to assess whether current market share is sustainable, whether pricing strategies are aligned with value perception in each segment, and whether portfolio gaps expose the organization to competitive encroachment. For executives evaluating market entry or expansion, the segmentation and regional analysis provide the due diligence foundation needed to assess addressable market size, competitive intensity, and the operational prerequisites for profitable participation.
Conclusion: Positioning for the 2026-2032 Cycle
The light switches and electrical sockets market is not defined solely by the steady expansion of its top-line figures. It is shaped by the interaction of residential renovation cycles, commercial construction activity, industrial specification requirements, smart home adoption curves, regulatory updates, and the competitive strategies of a concentrated group of global leaders alongside agile regional specialists. Understanding this complexity is the prerequisite for informed strategic action.
PW Consulting's market research provides the depth, structure, and forward-looking orientation that 2026 decision-makers require. By integrating historical performance, forecast trajectories, segmentation dynamics, competitive profiling, and regulatory context into a unified analytical framework, the report enables organizations to move from reactive adjustment to proactive strategy formulation. The market's projected growth path, combined with its evolving competitive and regulatory landscape, creates both opportunity and risk for those who lack detailed intelligence. Accessing the full report ensures that your organization enters this planning cycle with the clarity needed to allocate resources, differentiate offerings, and capture value in a market that continues to expand in both scale and sophistication.
For a complete view of the segmentation splits, regional revenue distribution, application-level demand shares, competitive benchmarking detail, and forecast model assumptions, we invite you to access the full market research report. The comprehensive dataset and strategic analysis contained within are designed to support the most demanding executive decision-making processes, and the full intelligence is available now for teams ready to translate market insight into strategic advantage.
For detailed analysis of this topic, please visit the official page: Light Switches and Electrical Sockets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Facial Water Spray Market Hits $215M in 2025, Projects 6.98% CAGR to 2032
By PW Consulting, 2026-09-07
Executive Preview: Why the 2026 Facial Water Spray Market Intelligence Is Critical for Strategic Decision-Making
The global beauty and personal care industry continues to consolidate around fast-moving, hydration-centric product categories, and the facial water spray segment has emerged as one of the most strategically sensitive arenas for 2026 planning and beyond. Our latest Facial Water Spray Market research study is designed to give executives, category managers, and innovation leads a decision-ready view of where the category is heading, how competitive intensity is reshaping pricing and distribution, and which underlying drivers will determine share performance over the next forecasting cycle. This article serves as a strategic preview of the full report. It demonstrates the analytical depth of our methodology and highlights the structural insights you can expect, while intentionally keeping the most granular breakdowns, exact segment valuations, and regional weightings inside the complete intelligence document.
Coconut Palm Spring Mattress Market
For leadership teams building 2026 roadmaps, the difference between a reactive category strategy and a durable advantage usually comes down to three questions: Is the market growing fast enough to justify capacity, supply chain upgrades, and channel expansion? Where is competitive pressure concentrating, and which players are actually changing the category rules in real time? What operational, regulatory, and consumer signals should be tracked so that product launches, packaging decisions, and go-to-market plans do not arrive too late? The full report is structured to answer those questions with a level of specificity that general industry commentary cannot match.
Heat Pipe Computer Cooler Market
The preview below summarizes the market context, the competitive architecture, the operational dynamics, and the practical contents of the study. It also explains how the research translates into strategic actions for product portfolios, regional prioritization, and partner ecosystem choices.
Paper Winders Market
Market Trajectory: Interpreting the Growth Curve for 2026 and Beyond
A credible category strategy begins with a disciplined reading of the market trajectory. In this study, the historical track record and forward projection are treated as more than a simple line on a chart. They are parsed to reveal where momentum is accelerating, where it is stabilizing, and which external forces are reshaping the path of expansion. The global market sizing reflects a category that has moved through a period of strong post-pandemic recalibration and is now entering a phase where growth is being shaped by ingredient differentiation, format refinement, and premiumization rather than by broad-based volume alone.
The research captures a multi-year time horizon that starts from a 2025 base, looks back across 2020 to 2025 for trend validation, and extends through a forecast window running to 2032. This structure matters because a single-year snapshot can hide cyclical behavior, launch effects, and the lag between innovation signals and commercial realization. The projection framework integrates both historical market behavior and the forward-looking dynamics that are likely to affect category performance, including formulation shifts, packaging modernization, and changing retail channel priorities.
For 2026 planning specifically, the forecast view provides an essential anchor. It helps organizations test whether current investment assumptions are consistent with the category’s expected growth cadence, and it supports more realistic budgeting for new production lines, marketing commitments, and channel development. Importantly, the report uses this trajectory to frame the strategic implications rather than simply presenting a top-line number. Readers can see how the pace of expansion interacts with competitive entry, pricing behavior, and product design choices.
Because the study is built to support executive decision-making, the narrative around the market size and growth rate is deliberately connected to commercial action. Rather than leaving leaders with a single aggregate expectation, the analysis ties the larger trajectory to the decisions that matter most: which product architecture to prioritize, how to think about premium versus mass-tier positioning, and where channel investment will generate the strongest return. The full report then extends this logic into more detailed views of segment behavior and regional performance, allowing teams to translate the macro trend into localized strategy.
What the Report Delivers: Operational Intelligence for Product, Portfolio, and Planning Teams
The full Facial Water Spray Market report is designed as a working document for cross-functional teams, not just a summary for senior review. It combines market sizing, segmentation logic, competitive profiling, regulatory context, and near-term industry movements into a single decision-support framework. The objective is to reduce the gap between market intelligence and execution.
One of the central contributions of the study is a structured segmentation model. The analysis breaks the category into meaningful product and application groupings and evaluates how each one contributes to the overall market architecture. This matters because facial water sprays are no longer treated as a simple commodity format. They are increasingly positioned around function, skin concern, ingredient narrative, and user experience. Organizations need to understand which segments are driving structural demand versus temporary promotion-led pull, and where the risk of overlap or internal cannibalization may emerge in a crowded portfolio.
The report also examines regional market performance, allowing readers to compare how the category behaves across major markets and to identify the differences in adoption, channel structure, and competitive pressure that shape regional outcomes. The full study is especially useful for companies evaluating export expansion, market entry, or reallocation of marketing spend. Instead of relying on broad assumptions, teams can use the regional comparison to ground portfolio prioritization and localization choices in a more defensible evidence base.
Beyond sizing and segmentation, the report integrates operational and regulatory context that directly affects product design and distribution. Cosmetic labeling expectations, origin identification for imported articles, net quantity and ingredient declaration rules, tamper-resistant packaging requirements for liquid products sold at retail, and labeling statements for self-pressurized containers are all relevant to how facial water sprays are developed, presented, and shipped. The study translates these requirements into practical implications so that compliance is treated as part of product strategy rather than a separate administrative task.
The research also addresses input and pricing dynamics that influence margin architecture and product positioning. Facial water sprays are primarily based on natural mineral or thermal spring water enriched with minerals and trace elements, and product variants that incorporate ingredients such as aloe vera, coconut water, rose water, and vitamin E tend to command premium pricing. This creates a strategic tension that the report explores in depth: how to build differentiation without eroding the perceived accessibility of the format, and how to align formulation investments with the pricing thresholds customers are willing to accept.
Competitive Architecture: Where Incumbents Stand and How the Field Is Shifting
The competitive landscape in facial water sprays is defined by a mix of heritage skin-care brands, thermal spring specialists, premium beauty houses, and specialized botanical or professional skincare players. The full report profiles leading companies and uses those profiles to show where distinct capability advantages are concentrated, how positioning differs across the category, and which strategic moves are likely to influence share dynamics in 2026 and beyond.
A defining feature of this field is the strength of French-origin brands with thermal spring and mineral-water heritage. Companies such as Avène, Evian, LA ROCHE-POSAY, DIOR, Vichy, Uriage, and Caudalie illustrate how heritage water sources, dermatological positioning, and premium ingredient narratives can be used to support both sensitive-skin care and high-end beauty use cases. These brands are not competing on the same promise. Some emphasize soothing and barrier support, others emphasize anti-aging and hydration benefits, and several leverage natural, botanical, or organic storytelling to justify premium price points.
At the same time, the competitive field is not limited to European premium players. Clinique and Origins bring formulation customization, clean skincare narratives, and dermatological or botanical positioning from a different commercial tradition, while Shu Uemura represents the high-end, professional-skincare angle where spring water is used to reinforce a more specialized beauty-service image. Together, these players show that facial water sprays sit at the intersection of function, sensory experience, brand prestige, and distribution context. The full report uses this competitive map to explain not only who is active, but where the category is becoming more crowded and where differentiation is becoming harder to sustain.
Market concentration data reinforces the strategic importance of this analysis. With a meaningful share held by a relatively concentrated group of leading players, competitive moves by incumbents can reshape pricing expectations, retailer behavior, and consumer perception quickly. The report uses this structure to examine how launch cadence, packaging innovation, ingredient storytelling, and channel targeting are likely to affect the field. Instead of treating competition as a static roster, the analysis connects company profiles to the behavior patterns that shape category leadership.
Recent activity from key players demonstrates how fast the strategic context can shift. La Roche-Posay expanded its thermal spring water spray line with eco-friendly recyclable packaging and enhanced mist technology for finer dispersion. Avène introduced a limited-edition sensitive-skin facial mist enriched with prebiotics designed to strengthen the skin microbiome. Evian partnered with K-beauty brands to co-create functional facial mists combining mineral water with regional botanical extracts for the Asian market. Clinique launched a travel-size facial water spray set with customizable scent infusions aimed at duty-free and online channels. These moves matter because they show the category advancing simultaneously on sustainability, microbiome and skin-function narratives, cross-cultural product collaboration, and channel-specific format engineering.
Market Dynamics: Regulation, Formulation, and Pricing as Strategic Levers
A category strategy for facial water sprays has to account for forces that are not strictly commercial but still determine product viability, cost structure, and time-to-market. In this research, regulation and sector dynamics are treated as active strategic variables rather than background noise.
On the regulatory side, the report addresses the labeling and packaging requirements that affect how imported and domestically sold cosmetic sprays are positioned and distributed. These include requirements for English country-of-origin naming on imported articles, ingredient declarations and net quantity statements for cosmetics, tamper-resistant packaging for liquid cosmetic products sold at retail, and specific labeling statements for products in self-pressurized containers. For product leaders, these requirements influence not only compliance workflows but also packaging architecture, claims development, and supply chain design. The full study shows how such rules can create both constraints and opportunities, especially when packaging modernization and format innovation are central to competitive positioning.
The formulation landscape is equally important. The category is anchored in natural mineral or thermal spring water enriched with minerals and trace elements, but the commercial differentiation increasingly comes from additions that support hydration, soothing, or premium sensory appeal. Ingredients such as aloe vera, coconut water, rose water, and vitamin E are associated with premium pricing behavior, which means formulation decisions directly affect brand positioning and margin structure. The report examines how ingredient selection, water source claims, and functional enrichment interact to shape consumer perception and pricing tolerance.
The combination of regulatory context, raw-material realities, and premium pricing dynamics creates a more complex competitive game than many category assessments assume. Companies that understand these dynamics can make better choices about claims, packaging, ingredient investment, and channel presentation. Companies that do not may launch products that are technically compliant but strategically misaligned. The full report is intended to reduce that risk by connecting regulation and formulation effects to commercial outcomes.
Strategic Uses of the Report for 2026 Decision-Making
The value of this research lies in how it can be used across the organization. For executive leadership, the study provides a consolidated market view that supports capital allocation, portfolio sequencing, and prioritization of innovation resources. For product and R&D teams, it offers a clearer basis for deciding which formulation directions, packaging formats, and functional claims are likely to perform in a competitive market. For commercial and channel teams, it helps frame where demand is most responsive and how to align format, size, and pricing with retail and online environments.
One of the most practical applications is portfolio architecture. Because facial water sprays can be positioned across sensitive skin care, daily hydration, premium beauty, botanical skincare, and professional skincare contexts, companies need a clear logic for where their own products fit and where overlap with existing offerings may create friction. The full report helps teams map category segments to product concepts so that portfolio expansion is deliberate rather than opportunistic.
Another key use is competitive response planning. With leading players actively modifying packaging, expanding functional claims, and pursuing cross-border collaborations, organizations need to understand which innovation directions are likely to become category norms and which are likely to remain differentiated. The study provides context for predicting where competitors may move next and where there is room for a credible alternative offering.
The report also supports market-entry and export decisions. Differences in regional performance, channel behavior, and regulatory environment mean that a facial water spray strategy that works in one market may need significant adaptation in another. The research gives leadership a more grounded basis for prioritizing expansion, tailoring localization, and assessing the operational complexity of entering or scaling in a given region.
Closing Preview: What the Full Study Unlocks
This preview is intended to demonstrate the analytical direction of the research and the strategic contexts it addresses. The complete Facial Water Spray Market report goes further by providing the detailed segmentation logic, deeper competitive profiling, region-by-region context, and applied scenario framing that decision-makers need to move from insight to action. It is built for teams that want more than a market summary: it offers a working framework for product planning, portfolio control, competitive monitoring, and compliance-aware execution.
For organizations shaping 2026 strategy, the central question is not whether the facial water spray category is relevant, but how to position within it with enough precision to win share without overcommitting to the wrong segment or the wrong competitive response. The full report is designed to answer that question with specificity. It gives readers the structure to interpret growth, the competitor context to anticipate moves, and the operational detail to convert strategy into product and channel decisions.
If your goal is to build a 2026 plan that is grounded in current market structure rather than assumptions, the complete study provides the intelligence needed to make those choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Facial Water Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com